📊 Full opportunity report: The Power Bottleneck: AI Data Centers and the Grid Cliff Approaching 2027-2028 on ThorstenMeyerAI.com — validation score, market gap, and execution plan.
Listen free for 30 days with Audible
Thousands of audiobooks and originals — cancel anytime.
Start your free trialAs an affiliate, we earn on qualifying purchases.
TL;DR
AI data center growth is constrained by power availability, with projections indicating a bottleneck by 2027-2028. This limits hyperscaler expansion despite massive capex commitments, due to slow grid upgrades. The situation poses risks for AI deployment timelines and costs.
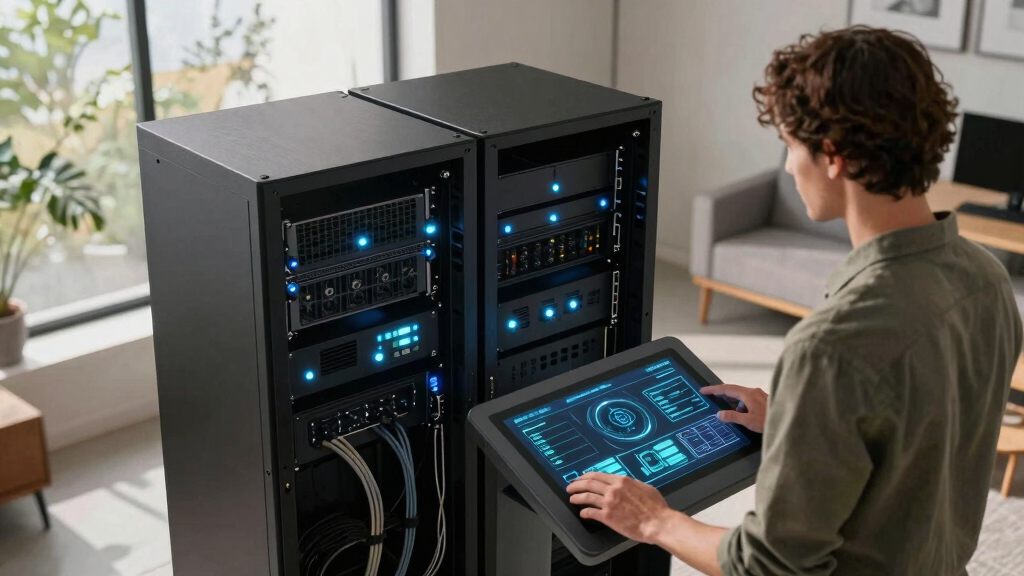
Power capacity limitations are now constraining the deployment of AI data centers globally, with the bottleneck expected to intensify by 2027-2028. Despite hyperscalers committing over $725 billion in capex, the pace of grid expansion and infrastructure upgrades is insufficient to meet the rising demand for AI workloads, threatening to delay or restrict growth.
In May 2026, industry reports highlighted that the mismatch between hyperscaler capex velocity and grid expansion timelines is a key barrier to scaling AI infrastructure. Microsoft announced a $15.2 billion investment in data centers in the UAE, citing regional power availability as a primary factor. Meanwhile, the PJM Interconnection’s recent capacity auction cleared at a record $15 billion, driven by data center demand outpacing grid capacity.
Experts like Nvidia CEO Jensen Huang have emphasized that power, rather than silicon, will be the rate-limiting factor for AI development in the coming years. Current estimates project that global AI data center electricity demand will reach approximately 1,050 TWh by 2026, making data centers the fifth-largest energy consumer worldwide. This growth is occurring at a 12% annual rate since 2017, four times faster than global electricity consumption.
However, the infrastructure required to support this demand—new transmission lines, base-load generation, and grid modifications—takes 4-10 years to implement, creating a significant delay compared to the 12-24 month capex deployment cycle. As a result, many regions face imminent saturation, with some already approaching grid limits, especially in Northern Virginia, Dublin, and Singapore.
Capex meets
the grid cliff.
Capex deploys in 12-24 months. Grid responds in 4-10 years. The mismatch is structural.
Global data center electricity 1,050 TWh by 2026 — fifth-largest in the world. Demand growth 12% CAGR vs 2-3% for total grid. Microsoft committed $15.2B to UAE for power-rich location. Three Mile Island restart 2028. PJM auction cleared $15B. AI service costs rise 5-20% through 2027-2028.
2024 → 2026 → 2030. The grid wasn’t designed for this.
Data center electricity demand has been compounding at 12% annually since 2017. Four times faster than total global electricity consumption. A single AI task uses up to 1,000× the electricity of a traditional web search.
Four strategies. None sufficient alone.
Geographic relocation · nuclear restart · off-grid microgrids · battery storage. Most hyperscaler strategies combine elements of all four.
Three paths. One constraint.
30/50/20 probability allocation reflects response-side execution uncertainty. Base scenario is most likely because the response strategies are real and beginning to deploy, but timelines are aggressive and execution risk is meaningful.
- Nuclear on timeTMI + SMRs deliver as announced.
- BYOP scales fastCrusoe-style proliferates.
- Costs +30-50%Plateau through 2028.
- AI prices +5-12%Pass-through manageable.
- Outcome: Capex deploys with 6-12 mo delays max.
- Nuclear delays 1-3ySMRs 18-36 mo late.
- Relocation acceleratesUAE / Norway / Iceland.
- Costs +50-80%New contracts.
- AI prices +12-20%Material pass-through.
- Outcome: Capex delays 12-24 mo systematic.
- Nuclear fails / delaysSMRs 24-48 mo late.
- Storage supply chainLithium / rare earths bind.
- Costs +80-120%Severe pass-through.
- AI prices +20-35%Demand destruction risk.
- Outcome: Capex delays 24-36 mo · impairment cycles 2028-29.
AI infrastructure is now an infrastructure problem more than a software problem. The companies that solve power constraint while solving the other constraints — architectural, capability, regulatory — capture durable advantage. The next 18-36 months produce the data on which side of the line each major player ends up on.
Four assignments. By role.
Update capex models for 12-24 month delays.
Differentiate on power-strategy quality: Microsoft (UAE + nuclear + microgrid) and Alphabet (Iceland + SMR + storage) best-positioned. Meta most exposed (mostly grid-dependent in Louisiana). Track nuclear-restart project execution as forward indicator. Power strategy is now material to capex returns.
Lock in long-term pricing now.
Negotiate hyperscaler partnership pricing now to lock current cost structure. Plan margin guidance for 5-20% service-cost uplift through 2026-2028. Evaluate alternative deployment regions (Norway, Iceland, UAE) for capacity expansion bypassing primary-market constraint. China sphere price gap compounds.
Begin scale expansion planning.
Transmission and substation expansion at scales matching DC load growth. Engage public utility commissions on rate-base investment + customer-class assignment. Develop time-of-use pricing incentivizing DC load profiles aligned with grid availability. Data center demand is structural, not transitional.
Negotiate with price-discount escalators.
Multi-region AI service architecture (US + Europe + Asia-Pacific) reduces single-region power-constraint exposure. Long-term commitments capture current pricing; short-term commitments preserve optionality but face upward repricing risk through 2027-2028. Geographic diversification matters now.
Impacts of Power Constraints on AI Expansion
The power bottleneck threatens to slow or halt AI data center expansion, risking delays in deploying AI services and increasing costs. This could impact the competitiveness of hyperscalers, raise operational expenses, and influence AI innovation timelines. Additionally, the rising costs of grid modifications are likely to be passed on to consumers, further affecting the economics of AI services.
uninterruptible power supply for data centers
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Rapid Growth of AI Data Center Power Demand
Since 2017, AI workloads have driven a 12% annual increase in data center electricity demand, now accounting for approximately 415 TWh in 2024—about 1.5% of global consumption. The demand is concentrated in regions with established hyperscaler presence, such as Northern Virginia, Dublin, and Singapore, where grid capacity is nearing saturation. Major hyperscalers like Microsoft, Amazon, and Alphabet have committed hundreds of billions in capex, aiming to expand capacity rapidly; however, infrastructure growth lags behind.
Grid expansion in the US, Europe, and Asia typically takes 4-8 years, contrasting sharply with the short timelines for deploying new data centers. The challenge is compounded by the increasing power density of AI racks, which now consume 80-150 kW per rack, up from 30-60 kW in 2024, demanding more robust power and cooling infrastructure.
“Power, not silicon, will be the rate-limiting factor for AI’s next phase.”
— Jensen Huang, Nvidia CEO
high-capacity data center cooling systems
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Uncertainties in Grid Expansion Timelines and Costs
While projections suggest a bottleneck by 2027-2028, the exact timing and severity depend on future grid upgrades, policy actions, and technological advances in energy storage and generation. It remains unclear how quickly regions will implement necessary infrastructure changes, and how costs will evolve, potentially affecting the pace of hyperscaler deployment.
energy-efficient server racks for AI
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Monitoring Infrastructure Developments and Policy Responses
Next steps include tracking grid expansion projects, regulatory approvals, and technological innovations that could alleviate power constraints. Industry stakeholders will likely accelerate investments in energy storage, nuclear, and renewable generation, while policymakers may prioritize faster grid upgrades. The timing and success of these efforts will determine whether the projected bottleneck materializes or is mitigated.
power monitoring systems for data centers
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Key Questions
Why is power capacity a bottleneck for AI data centers?
Because the rapid growth in AI workloads demands significantly more power than current grids can supply, and infrastructure upgrades take years, causing a mismatch between demand and capacity.
What regions are most affected by these power constraints?
Regions like Northern Virginia, Dublin, Singapore, and parts of the US and Europe are nearing grid saturation limits, impacting hyperscaler expansion plans.
How might this bottleneck impact AI development and services?
Potential delays in deploying new data centers could slow AI innovation, increase operational costs, and limit the availability of AI services to consumers and businesses.
Are there technological solutions to address this power constraint?
Advances in energy storage, nuclear power, and more efficient cooling could help, but large-scale infrastructure upgrades remain necessary and are time-consuming.
What can industry players do to mitigate these risks?
They can diversify geographic deployment, invest in local grid upgrades, and develop energy-efficient AI hardware to reduce power demands.
Source: ThorstenMeyerAI.com
NFL season / tailgating Picks
team gear
As an affiliate, we earn on qualifying purchases.