🔍 Read the full analysis: A Question Of AI: US Growth Rises While Hours Stay Nearly Flat on ThorstenMeyerAI.com

Get hardware and tech essentials delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
TL;DR
US business-sector output rose 10.0% from the fourth quarter of 2022 to the second quarter of 2026, while hours worked rose 0.9%, according to figures cited from BLS indexes. Productivity has accelerated, but the available data do not establish that AI caused the change; employment and pay trends also vary sharply across groups and industries.
US economic output is rising much faster than hours worked, according to government figures cited in a November 1 report, a gap that has fueled questions about whether artificial intelligence is changing the labor market. Business-sector output increased 10.0% from the fourth quarter of 2022 to the second quarter of 2026, while hours worked rose 0.9%; the data show stronger productivity but do not establish that AI caused it.
The Bureau of Economic Analysis’ advance estimate put real gross domestic product growth at a 3.4% annual rate in the third quarter of 2026, compared with 2.2% in the second quarter. Investment, consumer spending and government spending all contributed, according to the source report. The GDP figure measures the economy broadly; the productivity figures described below cover a narrower group of businesses.
For the nonfarm business sector, the Bureau of Labor Statistics reported that output grew 2.5% in the year to the second quarter of 2026, while hours worked increased 0.2%. Productivity rose 2.2% over that period. The report’s calculation from BLS indexes finds output up 10.0% and hours up 0.9% from the fourth quarter of 2022 through the second quarter of 2026, equivalent to productivity growth of roughly 2.5% a year over that span.
Employment growth has been uneven. The source says payrolls increased by 496,000 in the 12 months to September, with health care and social assistance adding 520,000 jobs. Information industries lost 120,000 jobs over the same period and remained 12% below their November 2022 peak. Those totals describe different sectors moving in opposite directions, not a uniform decline in employment.
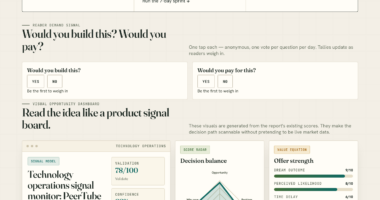
Infographic 01 · More output, same hours
Ten percent more output, almost the same hours
The US business sector produces much more than three years ago with almost no extra work. The new jobs are mostly in health care.
The last 12 months
Nonfarm business sector, Q2 2025 to Q2 2026
- Outputreal, value added+2.5%
- Productivityoutput per hour+2.2%
- Hours workedall workers+0.2%
Where the jobs went
Payroll jobs, change over 12 months to Sep 2026 (preliminary)
Since Q4 2022: output +10.0%, hours +0.9%, productivity +9.1% (my arithmetic from the BLS indexes). Hiring rate in Aug 2026: 3.3% of jobs (2019 average 3.9%); layoff rate 1.0% (2019: 1.2%). Correlation, not proof of cause.
Sources: BLS, Productivity and Costs Q2 2026 (3 Sep 2026) · BLS, Employment Situation Sep 2026 · BLS, JOLTS Aug 2026.
Powered by Thorsten Meyer AI
Productivity Gains, Uneven Payoffs
The gap between output and hours matters because productivity can rise when businesses produce more with the same labor input. Sustained productivity growth can support higher living standards, but it does not automatically show who receives the gains or whether workers are being displaced. The source report says labor’s share of business output fell to 52.8% in the second quarter, its lowest level in the series beginning in 1947, and that real private-sector wages fell 0.6% in the year to September. These measures point to pressure on workers’ share of income, though they do not identify a cause on their own.
Labor-market conditions also differ by age and race, according to the figures provided. Overall unemployment was 4.2%, compared with 8.0% for people aged 20 to 24 and 7.0% for Black workers. The report says those subgroup rates were up from 5.5% and 4.8%, respectively, in April 2023. Slow hiring can make it harder for people entering the workforce to find a first job even when layoffs remain low and total output is expanding.
For companies and workers, the practical issue is whether productivity gains translate into stronger pay, new roles or reduced demand for labor. The available figures show a growing economy alongside a comparatively weak increase in hours and uneven job outcomes. They do not, by themselves, resolve how much of the productivity change reflects new technology, investment, business-cycle effects or other factors.
Products Worth Considering
Apple MacBook Pro 16.2-inch with M5 Pro, 18-core CPU, 20-core GPU, 24GB Memory, 1TB SSD, Space Black

Apple MacBook Pro 14 2021 with M1 Max, 64GB RAM, 2TB SSD, Silver

LG UltraGear 27-Inch QHD OLED Gaming Monitor, 240Hz, 0.03ms, G-SYNC Compatible, FreeSync Premium Pro, HDMI 2.1
As an affiliate, we earn on qualifying purchases.
How the Output-Hours Gap Emerged
The productivity measure discussed here is output divided by hours worked. BLS’s nonfarm business-sector measure covers private businesses but excludes farms, government, nonprofits and households. It is therefore not interchangeable with GDP or a count of all jobs. A change in this measure shows that output per hour changed; it does not identify the mechanism behind that change.
The report compares recent productivity with earlier periods. It says productivity grew at an average annual rate of 2.1% from the end of 2019, against 1.5% a year from 2007 to 2019. It also uses the launch of ChatGPT on November 30, 2022, as a reference point for examining the period often associated with wider public attention to generative AI. A before-and-after comparison can describe timing, but it cannot establish that the launch or AI adoption produced the economic shift.
The report cites an early October Census Bureau measure indicating that about one in four US businesses said it used AI. That figure suggests adoption was not universal at the time of the survey, and it does not show how intensively businesses used AI or whether its use changed staffing or output. The report also notes that technology employment began shrinking before generative AI was widely used in business, complicating a simple causal account.
AI’s Role Is Not Established
The figures do not establish how much, if any, of the productivity increase is attributable to AI. The source report notes that only about one in four US businesses reported using AI in an early October survey, but does not provide a breakdown of adoption by firm size, industry or use case. Nor do the cited productivity statistics track whether firms that adopted AI subsequently produced more with fewer hours.
Other explanations may fit the same pattern, including investment in computers and software, changes in demand, shifts in the mix of industries and ordinary productivity fluctuations. The report says computers and software accounted for about a third of third-quarter growth, but that estimate does not isolate AI spending from other technology investment. The precise contribution of AI to output, hiring, wages and hours remains unclear.
The employment and wage figures also require careful interpretation. Payroll gains in health care and social assistance exceeded the overall reported increase, while information-sector employment fell; those facts do not show that workers moved between sectors or that AI directly eliminated particular jobs. The supplied material does not provide a full account of how the estimates may be revised or how the reported wage and labor-share measures compare across every industry.
More Data Needed on Adoption
The next useful evidence will come from updated BLS productivity, hours, employment and wage releases, alongside further GDP estimates from BEA. Those series can show whether the output-hours gap persists, narrows or changes as more quarterly data become available. The figures should be read with attention to their different coverage and time periods.
Further Census Bureau surveys and company-level evidence could clarify how widely businesses are adopting AI and whether adoption is associated with measurable changes in output, staffing or hours. Until those links are better documented, the data support a report of rising productivity and uneven labor-market conditions—not a definitive finding that AI is responsible. The source material does not specify a date for a new release or a particular next milestone.
Key Questions
How much did US business output and hours worked change?
From the fourth quarter of 2022 to the second quarter of 2026, the source report’s calculation from BLS indexes puts business-sector output growth at 10.0% and hours-worked growth at 0.9%. These figures describe the nonfarm business sector, not the entire economy.
Does the productivity data prove AI is replacing workers?
No. The data show output growing faster than hours worked, but they do not establish that AI caused the gap or that it directly replaced workers. Other explanations, including investment and changes in demand or industry mix, may also contribute.
What was the latest GDP growth figure cited?
BEA’s advance estimate put real GDP growth at a 3.4% annual rate in the third quarter of 2026, up from 2.2% in the second quarter. GDP is broader than the BLS nonfarm business-sector productivity measure.
Are jobs increasing in every industry?
No. The source says payrolls rose by 496,000 over the 12 months to September, while health care and social assistance added 520,000 and information industries lost 120,000. Those figures show sharply different employment trends across sectors.
How common was business use of AI?
The report cites an early October Census Bureau measure showing that about one in four US businesses said it used AI. The supplied material does not detail how intensive that use was or whether adopting firms changed their employment or output as a result.
Source: ThorstenMeyerAI.com